When a school needs room to grow but its bank says no
For an independent school, growing demand does not automatically make expansion easy to finance. Purchasing additional premises, adapting buildings or creating more pupil places can require significant investment before the extra income begins to arrive. When a bank declines the application, the next step is to understand the reasons and explore whether another lender or a different funding structure could suit the school’s plans.
Two perspectives on the same opportunity
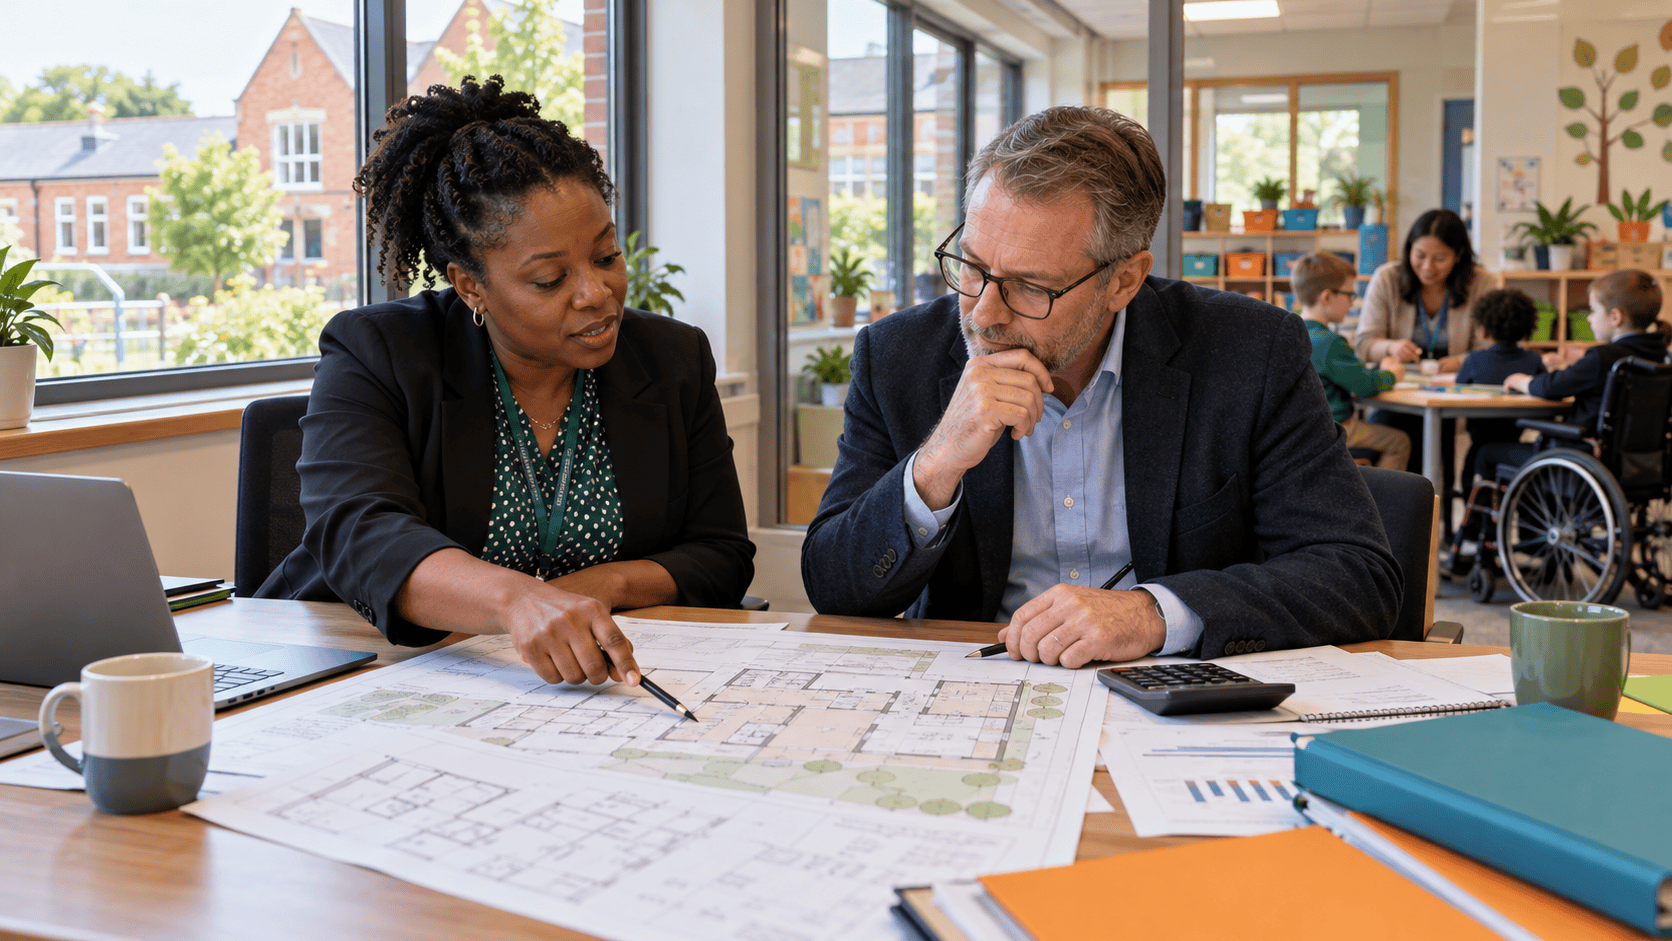
Our latest Expert Guide explores the position of a private school providing specialist education and support for children with special educational needs and disabilities (SEND). In its third year of trading, the school wanted to invest approximately £250,000 in classrooms, therapy space and specialist facilities.
Its bank had supported a property purchase the previous year, so approaching it again was a sensible first step. This time, however, the request was declined. The proposal did not fit that bank’s lending criteria.
The owner could see the opportunity to increase capacity and support more families. The bank needed to assess the risks of another substantial commitment, including construction costs, future income and the school’s ability to meet repayments throughout the project.
Neither view was unreasonable. They were looking at the same investment from different perspectives.
Understanding the funding gap
A strong reason to invest is an important starting point, but a lender also needs evidence of how the project will be delivered and repaid.
For a school, that means looking beyond the completed classrooms. Building payments may fall due before additional places can be offered. Staff may need to be recruited before pupil income increases. Existing borrowing and everyday running costs continue throughout.
An expansion that appears affordable once everything is operating could still create pressure during the months before completion.
That is why understanding the reason for a decline matters. A concern about construction risk calls for a different response from a concern about current affordability. Sending the same proposal elsewhere without addressing those questions may achieve very little.
Bringing the proposal together
This is where James and the FundingRound team can help. We start by understanding what the school wants to achieve, then examine the project through the questions a lender is likely to ask.
Recent accounts, current management information, existing borrowing, quotations, a realistic timetable and cash flow forecasts all help explain the proposal. Assumptions about additional pupils and fee income also need careful consideration.
Depending on the circumstances, different parts of the investment may suit different funding options. What matters is how the complete arrangement works for the school, including when repayments begin and how much room remains in its cash flow.
A wider choice of lenders can be useful, but it does not replace the need for a credible funding case. Sometimes the next step is an application. Sometimes it is strengthening the budget or revisiting the timing first.
Download the full Expert Guide
If you are planning investment in an education business, it offers a practical starting point for understanding what lenders may need to see before you commit to your next investment.
If it raises questions about your own plans, James and the FundingRound team would be happy to have an initial conversation.